Buying your first home in Oakland Park starts with more than finding a listing you love. A realistic budget, a mortgage comparison, and a clear understanding of inspections and contract deadlines can help you move from an offer to closing with confidence.
Start with the full cost of owning a home
A purchase price is only one part of the decision. Before touring homes in Oakland Park, look at your monthly income, existing debts, savings, and the amount you want to keep available for emergencies. Then work backward from a payment that feels manageable, not just the maximum a lender may approve.
Your monthly estimate should include mortgage principal and interest, property taxes, homeowners insurance, and any required mortgage insurance. Add association dues where applicable, along with utilities, maintenance, and a reserve for repairs. Insurance costs can vary considerably by property, so request an early quote rather than relying on a listing estimate.
Plan for cash needed beyond the down payment, too. Closing costs can include lender charges, title and settlement fees, prepaid taxes and insurance, and other transaction expenses. Inspections, an appraisal, moving costs, and immediate repairs may also affect how much cash you need. Ask your lender for a Loan Estimate and discuss which costs may be negotiable or paid by another party.
A comfortable monthly budget and sufficient cash after closing are just as important as the amount a lender is willing to finance.
For Florida properties, pay particular attention to windstorm and flood coverage. Standard homeowners policies generally do not cover flooding, and flood insurance requirements depend on the property and financing. Ask an insurance professional about coverage, deductibles, and available quotes before committing to a purchase.
Compare loans and get preapproved
Mortgage options differ in down payment requirements, mortgage insurance, interest rates, and eligibility. A conventional loan may offer several down payment options, while FHA loans have their own qualification and insurance rules. VA and USDA loans may be available to eligible borrowers or properties. Ask lenders which programs fit your circumstances rather than assuming one loan type is always the least expensive.
Request estimates from more than one lender and compare the interest rate, annual percentage rate, lender fees, mortgage insurance, and cash needed at closing. Also ask whether the rate is locked, for how long, and under what conditions. A lower advertised rate is not necessarily the best deal if it comes with substantially higher upfront costs.
For preapproval, lenders commonly review income, employment, assets, debts, and credit. A preapproval letter can help establish a shopping range and support an offer, but it is not a final loan commitment. Final approval generally depends on underwriting, the appraisal, and the property meeting the lender’s requirements.
Ask about assistance before you make an offer
Down payment or closing cost assistance may be available through state, local, or lender programs. Eligibility, funding, and application deadlines can change, and some programs require a homebuyer education course. Ask your lender which current programs you may qualify for and whether they can be combined with your chosen loan.
Choose homes to investigate, not just admire
Once your budget and financing plan are in place, compare available properties by layout, condition, and total carrying costs. Consider the features that matter to you: outdoor space, parking, access to parks or dining, and the routes you use regularly. Visit at different times when possible, and verify travel times and other priorities for yourself.
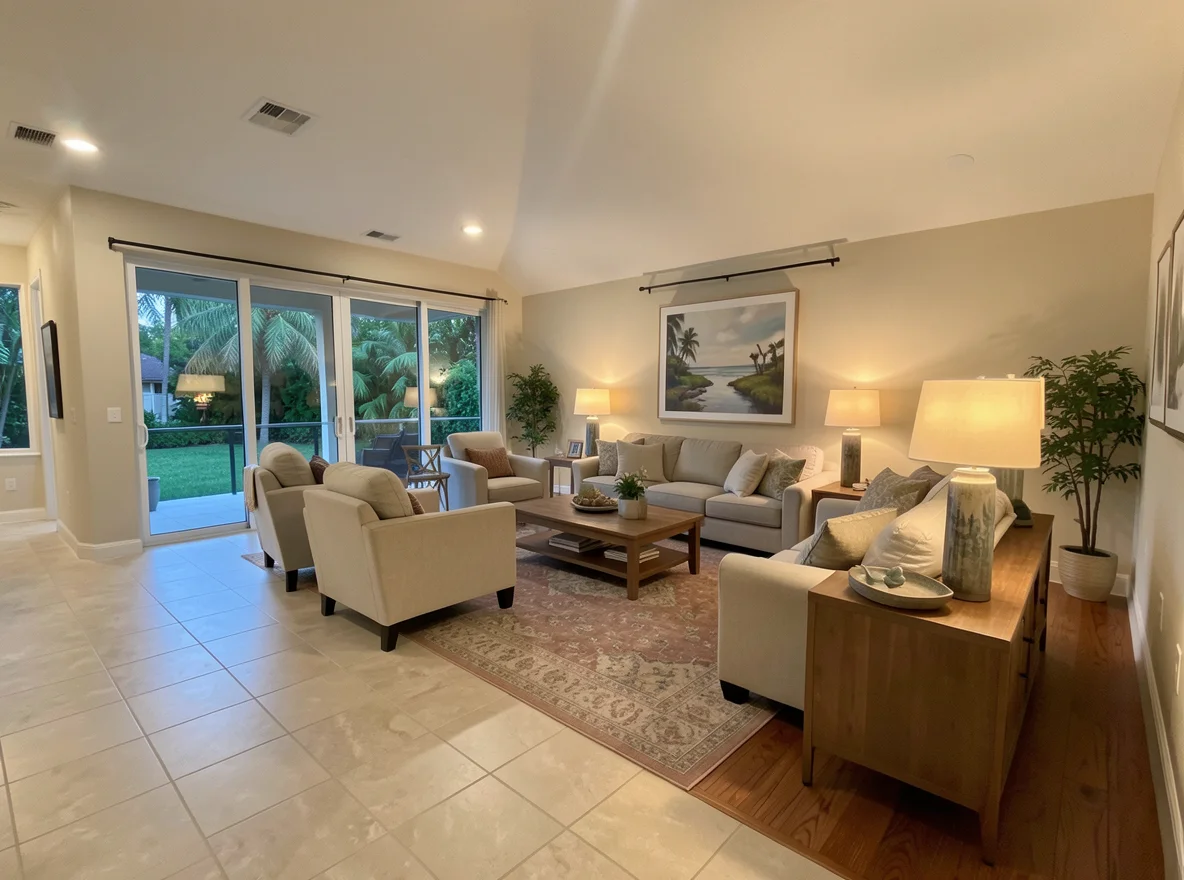
A property that looks affordable online may have costs that need closer review. Ask about the age and condition of the roof, air conditioning, plumbing, and electrical systems. An insurance provider may request a wind mitigation inspection or other property information before quoting coverage. Obtain estimates and professional advice rather than treating listing descriptions as a substitute for inspections.
If a home is part of a condominium or homeowners association, review the governing documents, budget, dues, rules, and any known special assessments. Ask about reserves, planned work, insurance responsibilities, and whether the property meets your lender’s requirements. The association’s costs and restrictions can influence both your budget and your day-to-day use of the property.
Property taxes deserve a separate check. The seller’s current bill may reflect exemptions or assessment limits that do not carry over to a new owner. Consult the Broward County property appraiser’s information and your tax professional for an estimate based on your circumstances; ask about homestead exemption eligibility and filing requirements as well.
Build an offer around price and protections
When you find a home, your agent can help you review comparable recent sales, property condition, competing activity, and your own budget. An offer includes more than price: it also addresses the deposit, financing, inspection rights, closing date, and other terms. The right combination depends on the property and your comfort with risk.
The earnest money deposit shows your commitment and is typically held by an escrow agent under the contract’s terms. Ask when it is due, how it will be credited at closing, and what happens if the transaction does not proceed. Do not assume a deposit is automatically refundable; the outcome depends on the contract and whether its requirements and deadlines are met.
Discuss financing, appraisal, and inspection contingencies with your agent before signing. These provisions can give you options if financing falls through, the appraisal is low, or an inspection reveals an issue, but their effect depends on the contract language. A seller may accept, reject, or counter your offer, so decide in advance which terms you can adjust and which are essential.
Contract deadlines matter: put inspection, financing, deposit, and closing dates on your calendar as soon as the agreement is signed.
Move from accepted offer to closing
After acceptance, schedule inspections promptly and review the findings with qualified professionals. Depending on the home, you may want to investigate the roof, major systems, pests, wind mitigation features, or other concerns. Your contract determines the inspection period and any available options for requesting repairs, negotiating, or canceling.
At the same time, your lender will continue underwriting and may order an appraisal. Respond quickly to document requests, avoid major financial changes without checking with your lender, and confirm that insurance can be obtained on terms you understand. If the appraisal comes in below the agreed price, discuss the contract and possible next steps with your agent and lender.
Title and settlement professionals will address the title search, closing documents, and payment arrangements. Review the Closing Disclosure carefully and compare it with your Loan Estimate; ask about charges or figures you do not understand. Lenders generally must provide the Closing Disclosure at least three business days before closing, subject to applicable rules. Confirm wiring instructions independently using a trusted phone number to help protect against fraud.
Before signing, arrange a final walkthrough to check the property’s condition and any agreed work. Bring the identification and funds requested by the closing agent, and keep copies of your signed documents. Once the transaction is complete and possession is delivered under the contract, you can turn your attention to settling in.
Talk with Sam about buying a home
From the first budget conversation to the final walkthrough, good preparation makes each decision easier to understand. Take time to compare your options, ask questions, and assemble a team that can help you evaluate the details of your Oakland Park purchase.